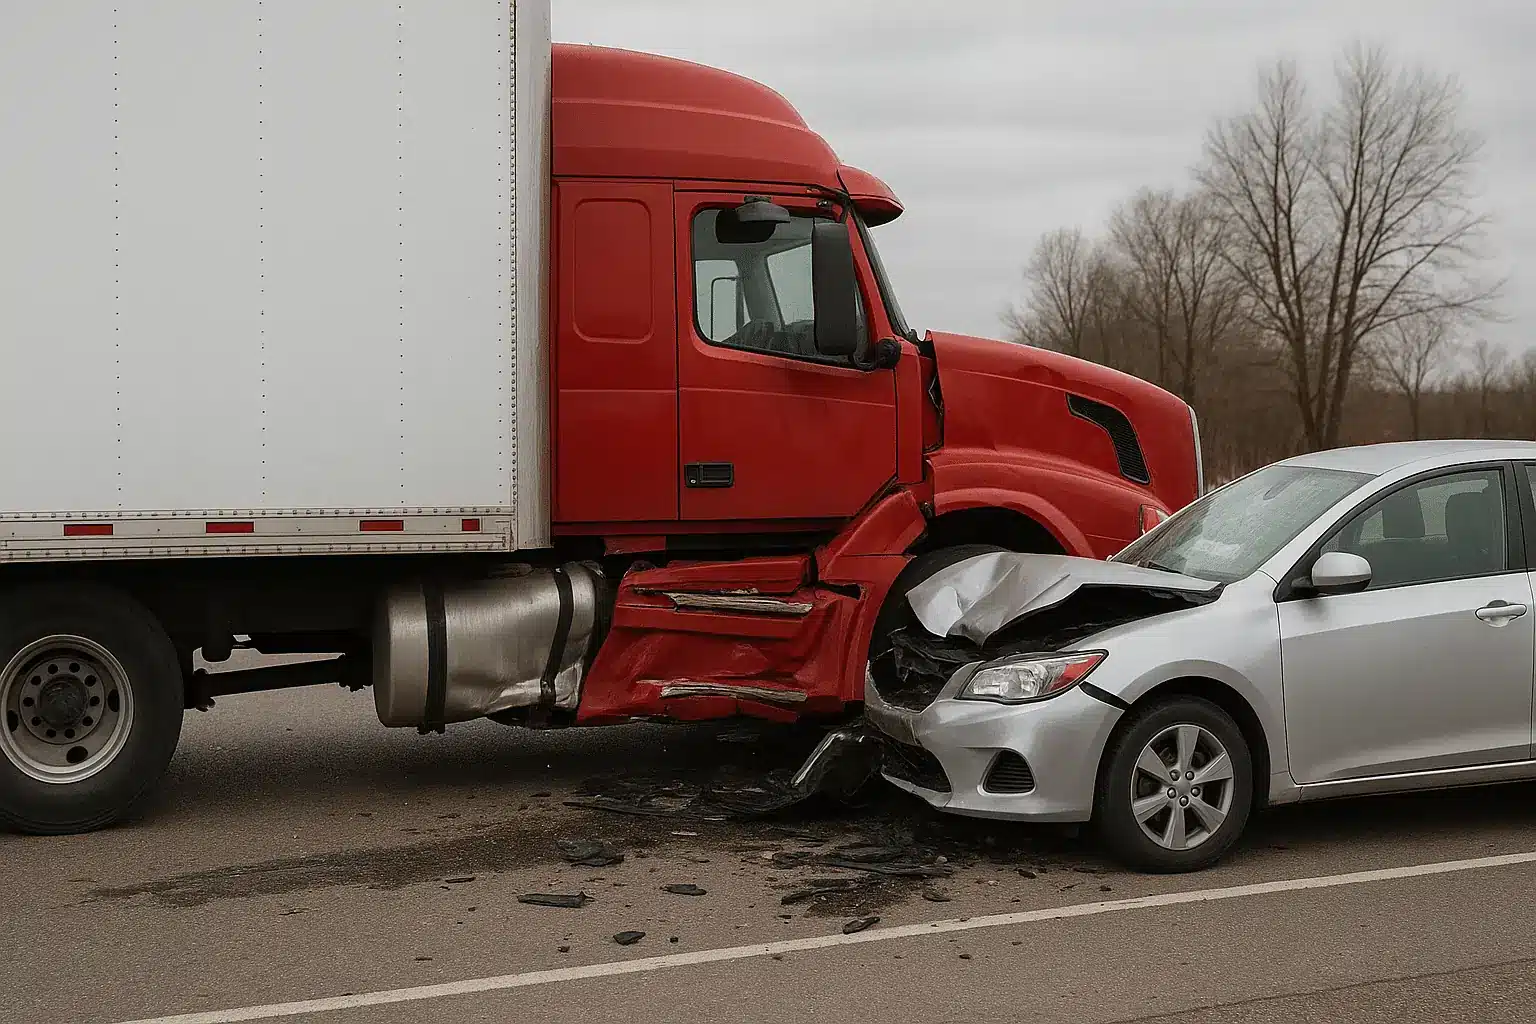
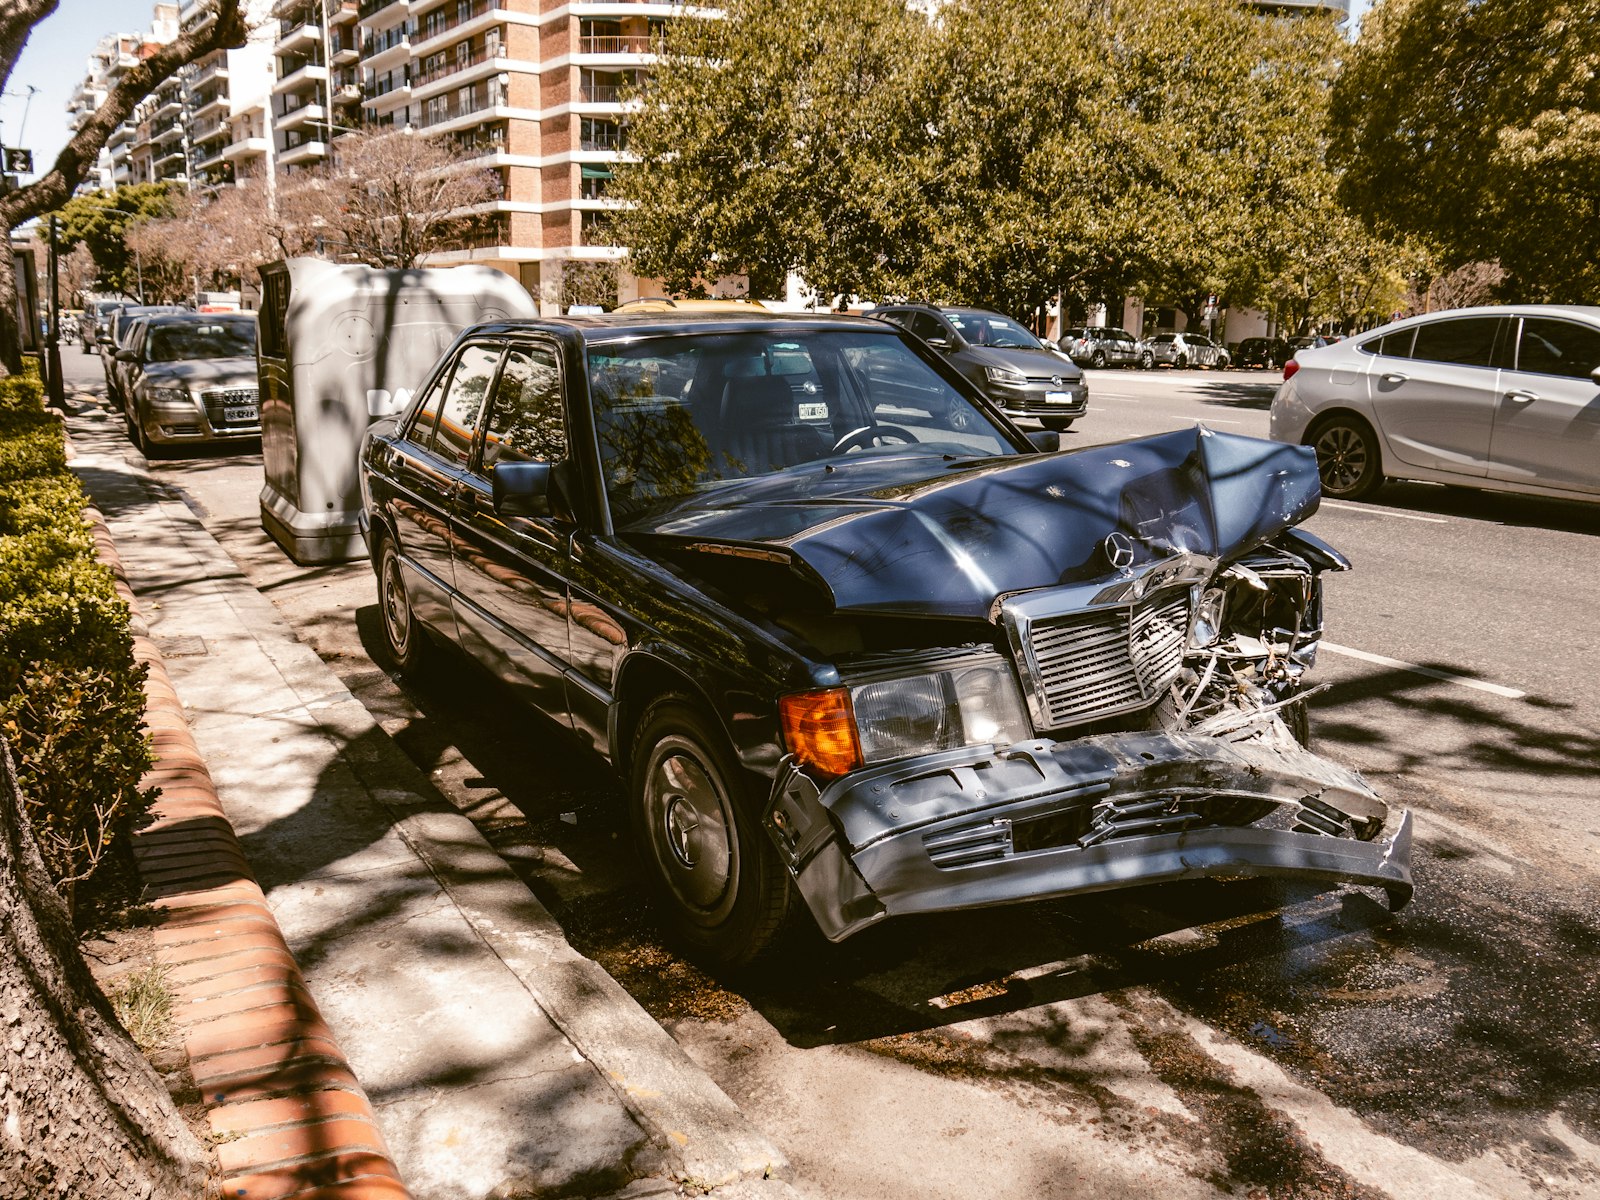
If you need to make an uninsured motorist claim in Missouri, you are not alone. Missouri requires every driver to carry liability insurance, yet a significant share of drivers on St. Louis roads carry none at all, with industry estimates putting it at roughly one in six. If one of them hits you, the good news is that Missouri law built in a safety net. The complicated news is that using it means making a claim against your own insurance company, and your own insurer will treat you a lot like the opposing insurers treat our other clients. We know, because we used to defend these claims.
The Safety Net: Mandatory Uninsured Motorist Coverage
Missouri is one of the states that requires uninsured motorist coverage in every auto policy. Under RSMo 379.203, your policy must include UM coverage of at least $25,000 per person and $50,000 per accident. You cannot waive it in Missouri, so if you have an auto policy, you have this coverage even if you have never looked at your declarations page.
UM coverage steps into the shoes of the uninsured driver. You must still prove the same things you would have to prove against that driver: that they were at fault, and what your injuries are worth. The difference is who pays.
Hit and Run Drivers Usually Count as Uninsured
If the driver who hit you fled and was never identified, most Missouri policies treat that phantom driver as uninsured, which means your UM coverage applies. Policies impose their own conditions on hit and run claims, such as prompt reporting and, in some policies, evidence of contact with the other vehicle, so report the crash to the police immediately and notify your insurer quickly. Photos of the damage and any witness information can make or break a phantom driver claim.
Stacking: The Coverage Most People Do Not Know They Have
Here is the part the insurance industry least likes to advertise. Missouri courts have repeatedly held that statutorily required UM coverage can often be stacked. That means if you insure three vehicles, or you are covered under more than one policy, the UM limits may add together rather than being confined to a single $25,000 limit.
Whether stacking applies depends on the policy language and the specific coverages involved, and insurers draft aggressively to limit it. But we have seen claims transform from a single minimum limit into several multiples of it once the policies were read the way Missouri law requires. Never assume the limit the adjuster quotes you is the real ceiling. Get every potentially applicable policy reviewed: yours, a resident family member’s, and any policy covering the vehicle you occupied.
Underinsured Motorist Coverage Is a Different Animal
UM coverage applies when the at fault driver has no insurance. Underinsured motorist coverage, or UIM, applies when the driver has insurance but not enough, which is common, since Missouri’s minimum liability limit is $25,000. Unlike UM, Missouri does not require UIM coverage, and whether it helps you depends heavily on the policy’s wording, including setoff language that can quietly shrink the coverage you thought you bought. Check your declarations page now, before you ever need it, and consider raising both UM and UIM limits. The additional premium is usually modest compared to the protection.
Your Own Insurer Is Not on Your Side in a UM Claim
This surprises people more than anything else. Once you make a UM claim, your insurer stands in the position of the uninsured driver, which makes it your legal adversary. The same company that cheerfully takes your premium will question fault, question your treatment, and value your claim with the same software and the same playbook the other side uses.
That is not cynicism, it is structure. The adjuster’s job on a UM file is to pay as little as the file allows. Everything we wrote about lowball tactics in our article on what to say to an insurance adjuster applies to your own carrier in a UM claim. Deadlines, consent to settle clauses, and arbitration provisions in your policy add traps that do not exist in an ordinary claim, which is why early advice matters.
What to Do After a Crash With an Uninsured Driver
Call the police and get a report, which documents the other driver’s lack of insurance. Photograph everything, get witness contacts, and seek medical care right away. Notify your own insurer promptly, but treat the conversation carefully: report the facts of the crash and decline to give a recorded statement about your injuries until you have advice. Then gather every auto policy in your household and have the coverage analyzed before you accept any number.
Frequently Asked Questions
Will my insurance rates go up if I make an uninsured motorist claim?
Making a UM claim for a crash that was not your fault should not be treated like an at fault accident, but rating practices vary by company. Whatever the rate consequences, they are almost never a reason to leave a meaningful injury claim unpaid. You bought this coverage, and Missouri law required it precisely for this situation.
The adjuster says the uninsured driver was partly my fault. What now?
Missouri follows pure comparative fault, so even shared blame does not bar your claim, it only reduces it by your percentage of fault. Adjusters routinely inflate the claimant’s share to justify a low offer. Push back with the police report, photos, and witness accounts, or have a lawyer do it.
How long do I have to make a UM claim in Missouri?
Lawsuit deadlines for UM claims are generally tied to contract limitations periods, which are longer than most injury deadlines, but your policy imposes much shorter notice and cooperation requirements, and hit and run claims often have strict prompt reporting conditions. Report quickly and get the policy reviewed early rather than relying on the outside deadline.
What if I was hit while walking or riding a bike?
Your auto policy’s UM coverage can still apply when an uninsured driver injures you as a pedestrian or cyclist. Household policies may apply too. This is one of the most commonly missed sources of recovery we see.
Former Insurance Defense Lawyers, Now on Your Side
We spent years handling claims for insurers, including UM claims against their own policyholders. If an uninsured or hit and run driver injured you in St. Louis or anywhere in Missouri, contact Sotiriou Wilmowski for a free consultation, or start with our overview of car accident cases.